When a judge ruled this summer that Zelle must face a lawsuit from New York Attorney General Letitia James, it wasn’t just a legal setback for the popular payment app—it was a wake-up call for an entire industry. The case, filed in 2025 against Early Warning Services, LLC, Zelle’s operator, alleges that weak safeguards allowed scammers to steal more than $1 billion from users between 2017 and 2023. While these remain allegations rather than findings of liability, the stakes are enormous. James is seeking restitution and damages for affected New Yorkers, along with court-ordered anti-fraud protections. At the heart of the matter lies a question every digital payment user should care about: how much security is built into the experience before the money disappears?
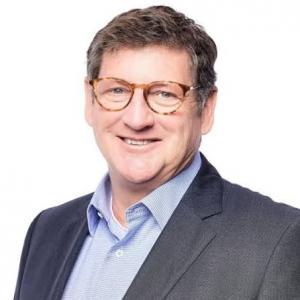
Bryan Lewis, president and CEO of Intellicheck, brings more than three decades of leadership in financial services and financial technology to this debate. His perspective cuts through the noise, focusing on identity verification as a foundational layer—not a silver bullet. “The broader issue raised by this lawsuit is whether adequate fraud prevention is built into the payment experience or treated as a response after the money is gone,” Lewis said. “Consumers want speed and convenience, but they also need confidence that the people and accounts they transact with are legitimate. Strong identity verification is an important starting point—not a substitute for transaction monitoring, scam detection, or a clear response when fraud occurs.”
Lewis is prepared to dive deeper into several critical topics: the role of identity verification when onboarding financial accounts, the distinction between document authentication and transaction-risk assessment, and the moments during a customer relationship when additional verification may be warranted. He also stresses that financial institutions must coordinate identity signals with broader fraud controls—and warns that no single technology should ever be marketed as a complete solution to payment scams.
Lewis’s background lends weight to his analysis. Before joining Intellicheck, he served as chief operating officer of Third Bridge, scaling the company from 100 to 600 employees in four years. He has held senior leadership roles at BondDesk, TheMarkets.com, Reuters, Barra, and Bloomberg, and began his career as a bond trader. He holds a Bachelor of Science in Economics from Penn State University.
Intellicheck itself is no stranger to the fight against fraud. The company, listed on Nasdaq as IDN, describes itself as the industry leader in identity verification management, preventing the use of unauthorized IDs to stop identity-based fraud. Its SaaS-based validation service uses proprietary analysis of DMV-issued IDs to deliver real-time verification across sectors, both in-person and digitally. According to the company, it processes identity transactions for nearly half the adult population in the United States and Canada annually, with 99.975% decisioning in under a second when customers use its tools to capture a document.
Why it matters: The Zelle lawsuit is more than a legal dispute—it’s a signal that regulators are no longer willing to accept after-the-fact fraud responses as sufficient. For consumers, the takeaway is clear: the convenience of instant payments must be matched by equally instant protections. For the industry, the challenge is to embed verification into the payment flow itself, not just clean up the mess afterward.